ALNG narrows Q3 loss to $5.9m as LNG spot rates sink below opex
ALNG cut its Q3 2026 net loss to $5.9m as TFDE spot rates fell to $9,500/day in September, then fixed WilPride and WilForce to an oil major in October to escape idle costs.
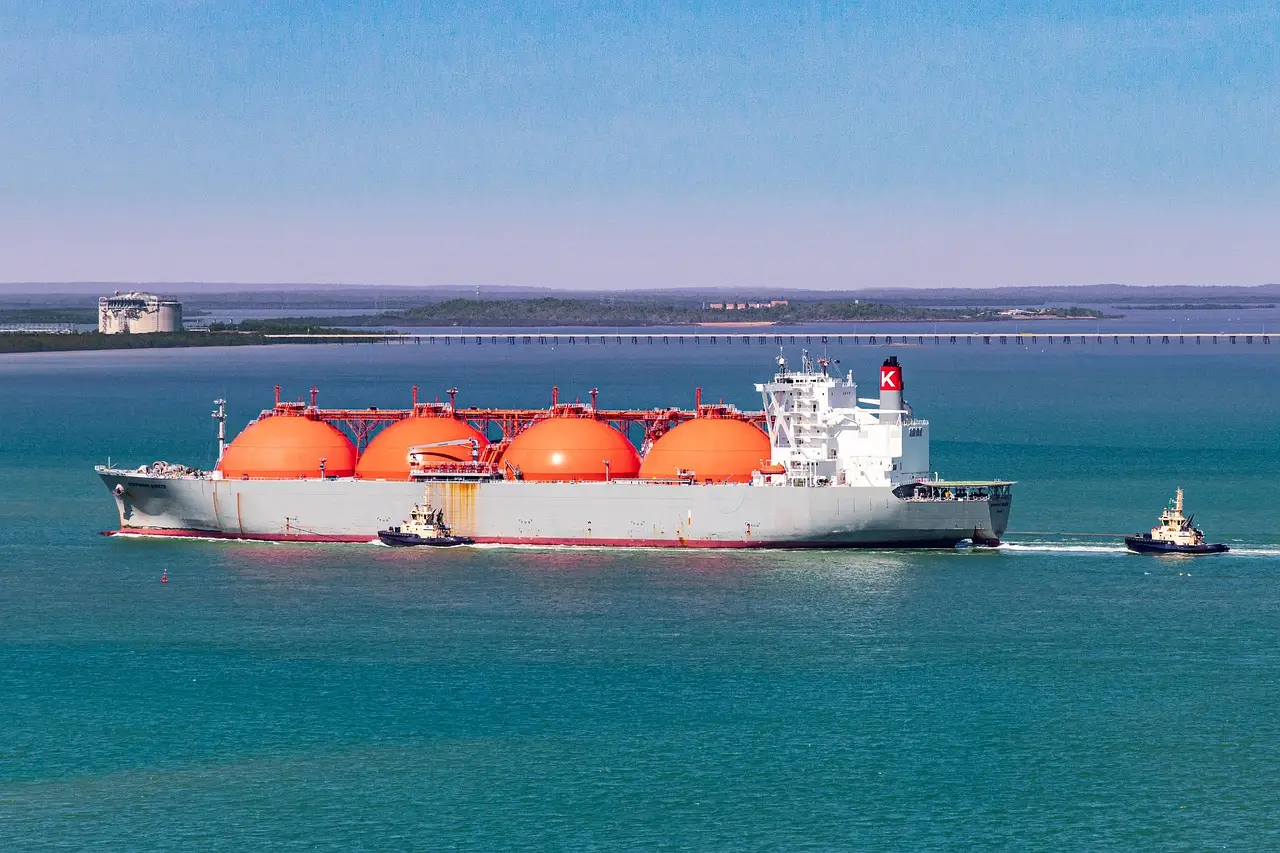
Adjustments
- Net loss of USD 5.9 million in Q3 2026, improved from USD 6.4 million in Q2; loss per share USD 0.03.
- Combined TCE of USD 38,400/day, up from USD 32,600/day; utilization 73% vs 66%.
- October period charters with an international oil major cover both WilPride and WilForce for worldwide trading.
- West of Suez TFDE spot averaged USD 28,000/day for the quarter, just USD 9,500/day in September — below opex.
- Orderbook of 285 vessels equals 36% of the 782-vessel conventional fleet, with 93 deliveries due in 2027.
ALNG ASA booked a net loss of USD 5.9 million for the third quarter of 2026, marginally better than the USD 6.4 million loss in Q2, with loss per share unchanged at USD 0.03. The number flatters the quarter. Spot rates for TFDE tonnage fell well below operating cost by end-August, and only an early-October period deal with an international oil major stopped the bleed.
Interim CEO Jens-Julius Nygaard put it plainly: too many ships chased too few cargoes, and rates dropped "to levels well below opex at the end of the quarter." The October time charters on WilPride and WilForce, he said, will "reduce the substantial cost of being idle with the current high gas prices."
What do the numbers show?
Top-line growth did not reach the bottom line. Freight income rose to USD 10.1 million from USD 7.3 million in Q2, but voyage expenses jumped to USD 3.0 million from USD 1.4 million on elevated fuel costs. Net freight income landed at USD 7.1 million against USD 5.9 million.
- EBITDA: USD 0.1 million, down from USD 0.6 million
- Opex: USD 4.1 million; admin: USD 2.9 million
- Depreciation: USD 3.8 million, flat quarter-on-quarter
- Net financial expenses: USD 2.2 million, down from USD 3.2 million after Q2's financing amendment costs were expensed
- Running interest on vessel financing: USD 2.7 million, SOFR-linked
Cash fell from USD 33.3 million to USD 29.8 million, with operating cash flow negative at USD 0.8 million. Interest-bearing debt held at USD 168.9 million under the amended CDBL lease terms. No scheduled lease amortization falls due before Q1 2028; deferred amounts run through 2029-2030, and rolling repurchase options started in June 2026. Book equity of USD 135.0 million on total assets of USD 312.0 million gives an equity ratio of 43.3%, down from 44.4%.
How bad was the spot market?
Third quarter split in two. July opened firm on Strait of Hormuz risk, with TFDE spot averaging roughly USD 60,000/day West of Suez and USD 50,000/day East, and modern two-stroke tonnage briefly topping USD 100,000/day in the Atlantic. Then TTF overtook JKM as Europe scrambled to rebuild record-low storage, the arbitrage closed, US cargoes shortened to intra-Atlantic runs, and tonne-mile demand collapsed just as prompt tonnage built in both basins.
The Atlantic two-stroke benchmark fell from about USD 96,000/day at end-July to USD 13,000/day by end-August. TFDE ships fixed at or below USD 10,000/day through August and September. For the quarter, West of Suez TFDE spot averaged USD 28,000/day — just USD 9,500/day in September — against roughly USD 62,000/day in Q2.
Supply did the damage as much as demand. Prompt availability almost doubled, 18 newbuilds delivered, and relet tonnage from portfolio players plus Qatar Energy's idle Gulf fleet took over half the spot market and 70% of multi-month fixtures. Fixture counts fell by a third to about 105, 84% single voyages; August-September saw the fewest spot fixtures of any two-month period since early 2024.
Period rates held up better: one-year two-stroke eased from USD 70,000/day in July to USD 49,000/day at quarter-end, one-year TFDE at USD 30,000/day, with charterers favouring index-linked structures.
What did the fleet actually earn?
WilPride rode her six-month charter above USD 70,000/day until redelivery in early September — straight into the quarter's weakest point. WilForce traded spot with idle periods throughout. Combined TCE still reached USD 38,400/day, up from USD 32,600, ahead of the TFDE spot averages purely on WilPride's cover through August. Utilization improved to 73% from 66%.
The October fix to the oil major covers both vessels for worldwide trading, final period dependent on conditions. Rates are "at favourable levels," the company says. The total financial impact over the duration is uncertain. Realized income won't appear until the Q4 report — so treat the promise as provisional.
How does the supply picture look?
Global loadings hit 103 million tonnes, up about 5 MT on Q2, on record US output from Plaquemines and Corpus Christi Stage 3. Qatari exports sat at roughly a quarter of pre-war volumes, with around half the Gulf-dedicated fleet idle, though Hormuz LNG transits rose to 45 in September, the most since the war began. European imports fell 16% to 22 MT while North Asia took 56 MT, up 11%. EU storage closed September at 71%, the lowest for the date since 2011. TTF and JKM both ended the quarter above USD 24/MMBtu.
The conventional fleet reached 782 vessels after the 18 deliveries; 13 were ordered and none scrapped. The orderbook stands at 285 vessels, 36% of the fleet, with 31 deliveries due in Q4 and 93 in 2027. S&P stayed active at 21 transactions year-to-date.
What happens next?
ALNG expects the weak spot market to persist through the prolonged Iran-US conflict, and declines to forecast a reopening timeline for regional production. The LNG trading platform, built after the first-half capital raise, is progressing slower than planned — the company blames gas prices — and the first trade has yet to materialize. Nine onshore staff run commercial management from Oslo and London. The caveat sits in every line: the winter bet rests on one oil major's contract and a European storage deficit.
via Hellenic Shipping News (Source)
More from James Calloway
Show full bio
Correspondent covering technology and product news in commercial shipping for industry professionals at Vessels.
66 articles
Linked entries
- ZIM’s $830M Q3 profit lifts 2026 EBITDA target to $3.5B
- ZIM lifts 2026 adjusted EBITDA outlook again on 55% freight-rate jump
- CMA CGM lifts volumes 5.5% and revenue 31% in third quarter
- ALNG pulls entire fleet off spot with oil major charters
- ZIM triples quarterly profit to $830m as freight rates jump 55%